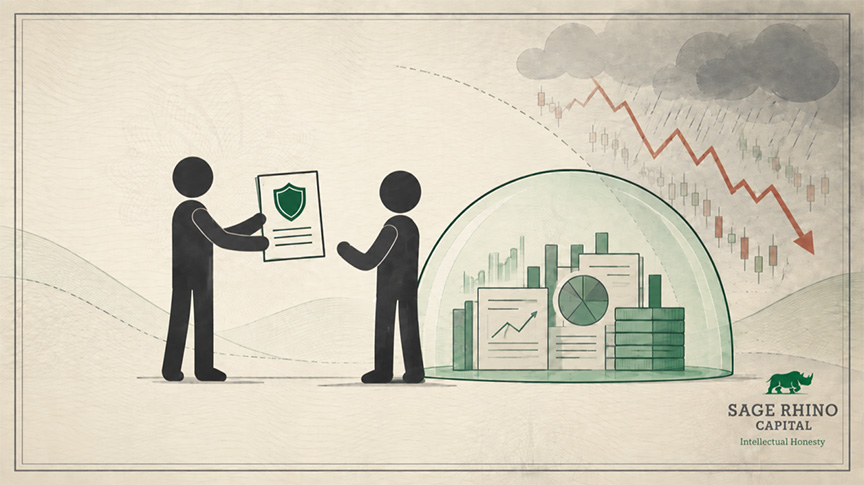
Everyone pays for insurance. Health insurance. Car insurance. Home insurance. Pet insurance. You name it, and there is insurance for it. But who has portfolio insurance? Why can’t the value of a portfolio be insured, in case of damage, like property or someone’s health? It turns out it can, and here’s how.
The Mechanics – Simplified
Portfolio insurance is not as simple as calling a broker and getting a policy that ensures the current value of your portfolio doesn’t drop. If that were the case, everyone would already have it. Portfolio insurance, or the best representation of it in financial markets, uses options to hedge positions.
This issue will not cover the topic from A to Z. It will explain the basic mechanics to spur further investigation. Here we go!
A “put” is a type of option that gives the holder the right to sell the underlying security at the contract’s strike price. For example, if you hold an Apple 225 put, you have the right to sell your shares at $225. If the price of apple drops from $240 to $215, the holder can sell their apple shares at $225 even though the market price is currently $215, through a process called “exercising”. The holder of the put can also sell the put, which would be worth approximately $10, the difference between the strike price and the current market price. This increase in the price of the put is what allows the holder, who is trying to hedge their portfolio without selling, to recognize a financial benefit while not selling the underlying shares.
The Other Side
Why not just sell the portfolio if the expectation is that the market will go down over the next year? Instead of buying portfolio insurance, wouldn’t it make sense to sell outright and buy back later?
Selling could incur capital gains, short term or long term, and that bill must be paid even if funds are placed back in the market after the draw down. Is sideline cash used to pay that bill, or will it come from the sales proceeds? It is possible that the tax bill might exceed the savings from selling and re-entering.
The market might not come down as expected. The shares are sold, the portfolio has the cash, but market goes higher, leaving the seller behind. Portfolio insurance costs a premium, but it keeps exposure to the market in case the decline doesn’t play out.
“If I’m willing to ride out market volatility, is this necessary?”
It’s different for every person. Just like any other insurance or hedging strategy, the necessity, or even usefulness varies case by case. Homeowners that pay premiums for 20 years and never make a claim are in a similar situation. The cash that went to premiums could have been invested in home improvements increasing the value of the property. Insurance was held in case there was damage, not because damage was expected.
Worth Exploring?
Like any other type of insurance, there are many moving parts, and it is not one size fits all. From protecting the value of a concentrated, illiquid position, from employment compensation or selling a business, to hedging overall market risk, the options are nearly endless.
Insurance isn’t obtained because you expect something to happen, it’s there in case the unexpected occurs.