The Question
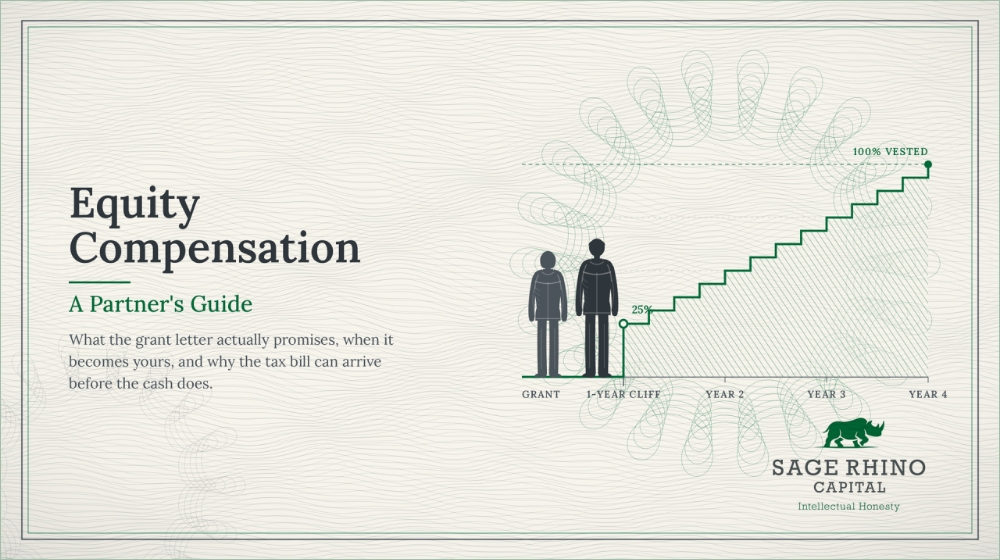
Equity compensation — can we spend it?
It’s a fair question, and it comes up in more households than you’d think — tax season, a year-end statement, a stray mention of “vesting” at dinner. The number on the form is real. The account balance is also real. The gap between them isn’t a mistake — it’s RSUs, stock options, or an ESPP, three very different things that all get lumped together as “equity” and all show up on paper before they show up as cash, if they ever do.
This issue’s for the spouse asking that question.
Three Angles
I. RSUs (Restricted Stock Units) — the closest thing to a stock bonus.
An RSU is a promise: stay long enough, hit the vesting schedule, and the company hands over actual shares — no purchase required. At a public company, those shares are liquid stock the moment they land, and the value at vesting is simply added to that year’s taxable income, the same as a cash bonus would be. At a private company, the mechanics are similar, but the shares often can’t be sold until a liquidity event — an IPO or acquisition — actually happens, so “vested” and “spendable” aren’t the same thing. What RSUs optimize for is simplicity: nothing needs to be decided or paid for. What they cost you is certainty about the number itself — the value your partner quotes at the start of the year depends on a stock price nobody can predict, so it’s a moving target dressed up as a fixed one.
II. Options (ISOs and NSOs) — the closest thing to a bet.
A stock option isn’t stock — it’s the right to buy stock later, at a price fixed today (the “strike price”). If the company’s value climbs well above that price, the option becomes valuable; if it doesn’t, the option can simply expire worthless. Unlike RSUs, nothing happens automatically: your partner has to actively decide to “exercise” — meaning pay cash, out of pocket, to actually buy the shares — often with a deadline attached, both at private and public companies, and sometimes on a clock as short as 90 days if they leave the company. The tax treatment splits into two flavors that behave very differently: incentive stock options (ISOs) can qualify for more favorable tax treatment later, but only if strict holding rules are followed and can trigger a separate tax (AMT) at exercise; non-qualified options (NSOs) create a taxable event at exercise regardless. What options optimize for is upside — the ability to buy low if things go well. What they cost is that “going well” is not guaranteed, and getting there requires your household putting up real cash for shares that could still end up worth less than what was paid.
III. ESPPs (Employee Stock Purchase Plans) — the closest thing to a guaranteed discount.
An ESPP lets an employee set aside part of their paycheck, then use it to buy company stock — typically at a 10–15% discount to the market price — through payroll deductions, almost always at public companies. Unlike options, there’s no bet on the stock rising to make it worthwhile; the discount alone is usually value that wasn’t there before. What ESPPs optimize for is a near-sure thing. What they cost is concentration: it’s a plan that automatically routes household savings into more of the same single stock your partner’s paycheck, RSUs, and options may already be tied to — and unlike the other two, participating is itself a choice made every enrollment period, not something that just happens in the background.
What’s Being Said
At Google, a senior-level (L5) software engineer’s median annual package breaks down to roughly $228K in base salary, $161K in stock, and $28K in bonus — stock alone is already close to 40% of total pay. Climb to a senior director level (L8), and the split flips: base salary is around $360K, but stock is roughly $798K — well over half of a package that now totals more than $1.28M. The higher someone climbs, the less their pay looks like a salary at all.
Where to Start
Not with the dollar figure — with the label. “I have equity” isn’t specific enough to plan around; “I have RSUs vesting quarterly,” “I have ISOs I haven’t exercised,” and “I’m enrolled in the ESPP” are three different financial situations with three different sets of deadlines, cash requirements, and tax consequences. The first useful conversation isn’t about how much it’s worth — it’s about which of the three you’re actually looking at, and whether it’s at a public company (where the stock trades daily and can generally be sold once vested or exercised) or a private one (where “worth it” may not be spendable until a future event that hasn’t happened yet).
The Reframe
“The paycheck arrives and asks nothing of you. Equity compensation arrives and asks a question — and until someone answers it, nobody actually knows what it’s worth.”
Sources
Levels.fyi, a crowdsourced tech-industry compensation database, for the base/stock/bonus breakdown statistic; National Association of Stock Plan Professionals (NASPP) for general RSU mechanics and terminology conventions used throughout.
#StockOptions #EmployeeLiquidity #PrivateCompanyShares #WealthManagement #TaxPlanning